What Is a Good Car Loan Rate in Canada? Typical APRs, Examples & How to Compare
January 13, 2026
Last updated: October 2026
What is a good car loan rate in Canada in 2026? A good car loan rate is one that is competitive for your credit profile, the vehicle you are buying and the repayment term you choose. As a reference point, the Bank of Canada reported an average rate of 6.66% in July 2026 for newly advanced and renewed auto loans at reporting chartered banks.
That figure is a useful national benchmark, but it is not a guaranteed rate, an advertised APR or an average covering every Canadian auto lender. Your actual offer could be lower or considerably higher depending on your circumstances.
The best way to judge whether a car loan rate is good is to compare similar financing offers, check the full cost of borrowing and choose payments that fit comfortably within your budget.
What Is Considered a Good Car Loan Rate in Canada?
There is no single interest rate that is considered good for every Canadian borrower.
Someone with excellent credit purchasing a new vehicle may qualify for a different rate from someone with a limited credit history financing an older used car. Even two borrowers with similar credit scores may receive different offers.
When assessing a rate, consider these questions:
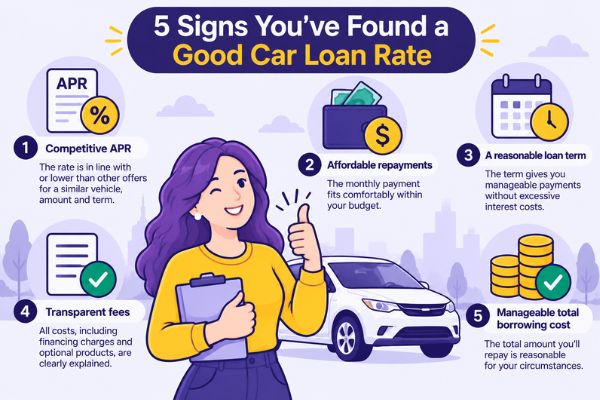
- Is the rate competitive? How does it compare with offers for a similar vehicle, loan amount and repayment term?
- Does it reflect your credit profile? Lenders may assess your credit history, income, debt obligations and overall affordability.
- Is the repayment term reasonable? A lower monthly payment is not necessarily a better deal if the loan lasts several extra years.
- What is the total borrowing cost? Interest and applicable financing charges can add thousands of dollars to the amount you repay.
- Can you afford the full cost of owning the car? Your budget also needs room for insurance, fuel, maintenance and unexpected repairs.
Bottom line: A good car loan rate is not simply the lowest advertised percentage. It is a competitive offer with transparent costs and a repayment structure you can afford.
Average Car Loan Interest Rate in Canada: 2026 Benchmark
The Bank of Canada publishes monthly interest-rate statistics for auto lending by reporting chartered banks.
Its July 2026 figure provides a useful starting point when assessing the broader lending environment.
| Bank of Canada auto lending measure | July 2026 rate |
|---|---|
| Newly advanced and renewed auto loans | 6.66% |
| Outstanding auto loan balances | 6.83% |
Source: Bank of Canada, Interest Rates for New and Existing Lending by Chartered Banks, series V122667805 and V122667811, July 2026. The newly advanced and renewed auto loan measure is volume-weighted and does not represent all Canadian auto lenders or every borrower’s available rate.
Does That Mean 6.66% Is a Good Car Loan Rate?
A rate around the reported bank benchmark may be worth comparing with other offers, but the benchmark alone cannot tell you whether a particular loan is competitive.
For example, manufacturer-supported promotional financing may be available at lower rates on selected new vehicles. Conversely, borrowers with weaker credit profiles or vehicles that do not meet standard lending criteria may be offered higher rates.
It is also important to distinguish the Bank of Canada’s reported interest-rate measure from the disclosed annual percentage rate (APR) on an individual financing agreement. The APR may account for certain financing charges in addition to interest.
For a closer look at the monthly figures, read our guide to the average car loan interest rate in Canada.
What Is a Good Car Loan Rate for Your Credit Score?
Your credit history can influence the financing offers available to you, but Canadian lenders do not follow one universal table that assigns an APR to each credit-score range.
Generally, applicants with stronger credit profiles may qualify for more competitive rates, while applicants with fair, poor or limited credit histories may face higher borrowing costs or additional conditions.
| Credit profile | What to consider when comparing rates |
|---|---|
| Excellent or very good credit | Compare competitive bank, dealership and manufacturer financing offers. Do not assume the first advertised rate is the lowest available. |
| Good credit | Compare several offers with the same loan amount and term. Differences in vehicle eligibility and affordability assessments can affect pricing. |
| Fair credit | Look closely at the total borrowing cost, financing conditions and whether a larger down payment could improve affordability. |
| Poor or rebuilding credit | Consider whether the proposed payments and total interest are sustainable. Avoid accepting expensive financing simply because approval is available. |
| Limited or no credit history | Ask what income, employment, down payment or other information the lender may consider when assessing your application. |
These descriptions are general guidance, not official credit-score-specific APR ranges or approval thresholds.
For a more detailed explanation, see our guide to car loan rates by credit score in Canada.
How Much Does a Good Car Loan Rate Save You?
Even a relatively small change in interest rate can make a meaningful difference over the life of a car loan.
Consider a $30,000 loan repaid over 60 months at different fixed annual interest rates.
| Annual Interest Rate | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|
| 5% | $566 | $3,968 |
| 7% | $594 | $5,642 |
| 10% | $637 | $8,245 |
| 15% | $714 | $12,822 |
| 20% | $795 | $17,689 |
Example assumptions: $30,000 financed over 60 months at a fixed annual interest rate, with monthly compounding and equal monthly payments. Figures are illustrative and rounded. Taxes, fees, optional products and other charges are excluded. These percentages are not advertised rates or rates assigned to particular credit-score categories.
At 5% interest, the borrower pays approximately $3,968 in interest over five years. At 10%, the interest cost rises to approximately $8,245.
That is about $4,277 more in interest on the same $30,000 loan.
These examples show why comparing rates matters, even when two offers have monthly payments that initially seem manageable.
You can test your own loan amount, rate and term using our car loan calculator.
Are Good Car Loan Rates Different for New and Used Cars?
They can be. New and used vehicles may qualify for different financing programs, and the age, mileage, condition and value of a vehicle can influence lender eligibility and pricing.
Some manufacturers offer promotional rates on selected new vehicles. Used vehicles generally do not have access to the same manufacturer incentives, although competitive financing may still be available.
| Vehicle Type | What Can Affect the Financing Rate? |
|---|---|
| New vehicle | Manufacturer promotions, lender programs, purchase price, down payment and borrower eligibility. |
| Certified pre-owned vehicle | Whether the vehicle qualifies for a specific certified financing program, plus its age and value. |
| Used vehicle from a dealership | Vehicle age, mileage, condition, loan-to-value ratio and lender restrictions. |
| Used vehicle from a private seller | Availability of financing products, vehicle eligibility, collateral requirements and the lender’s policies. |
A lower interest rate on a new car does not automatically make that car cheaper overall. The purchase price, depreciation, insurance costs and amount financed still matter.
For more detail, see our guide to new versus used car loan rates in Canada.
Does a Shorter Car Loan Term Mean a Better Rate?
Not necessarily. Some lenders offer different interest rates depending on the loan term, but there is no universal rule that every shorter loan has a lower APR.
What is more predictable is the effect of the repayment term on total interest: when the loan amount and interest rate stay the same, a longer repayment period generally increases the total interest paid.
Consider the same $30,000 loan at a fixed annual interest rate of 7%.
| Loan Term | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|
| 48 months | $718 | $4,483 |
| 60 months | $594 | $5,642 |
| 72 months | $511 | $6,826 |
| 84 months | $453 | $8,034 |
Example assumptions: $30,000 financed at a fixed annual interest rate of 7%, with monthly compounding and equal monthly payments. Figures are illustrative and rounded, excluding fees, taxes and other charges.
The 84-month option has the lowest monthly payment, but it costs approximately $3,551 more in interest than the 48-month option.
Longer loans can also increase the risk of negative equity, where the amount you owe exceeds the vehicle’s value.
The Financial Consumer Agency of Canada advises borrowers to consider the risks of long-term car loans and choose the shortest repayment term they can reasonably afford.
Interest Rate vs APR: Which Number Tells You if a Car Loan Is Good?
When comparing financing offers, pay attention to both the stated interest rate and the disclosed annual percentage rate (APR).
The interest rate describes the rate charged on the outstanding loan balance.
The APR is an annualized measure of borrowing costs calculated under applicable disclosure requirements. Depending on the agreement and relevant rules, it may include certain financing charges in addition to interest.
Not every cost associated with buying or financing a vehicle is necessarily included in the APR.
Before accepting an offer, compare:
- The stated interest rate and disclosed APR.
- The total amount being financed.
- Any applicable financing fees.
- The monthly or other scheduled payments.
- The repayment term.
- The total cost of borrowing.
- Optional products or services included in the financing.
- Early repayment conditions.
If two offers have different terms or amounts financed, the lower APR does not necessarily mean the lower total dollar cost.
Read our guide to car loan interest rates versus APR in Canada for a fuller explanation.
How to Tell Whether Your Car Loan Offer Is Competitive
Rather than deciding that a particular percentage is automatically good or bad, use the following process to evaluate the offer in front of you.
1. Compare More Than One Financing Offer
Where possible, obtain comparable quotes from different financing sources, such as your bank or credit union and dealership-arranged lenders.
The Financial Consumer Agency of Canada notes that a dealership does not have to present the lowest available financing rate. Shopping around may help you identify a more competitive offer.
2. Compare the Same Loan Amount and Term
Comparing a 48-month loan with an 84-month loan based only on monthly payments can be misleading.
Start by comparing offers for the same amount financed and repayment period. Then evaluate whether changing the term improves affordability without creating excessive borrowing costs.
3. Look at the Total Cost of Borrowing
Ask for a clear breakdown of the amount financed, interest, financing charges and total repayment obligation.
A lower monthly payment can hide a substantially higher overall cost when the loan is extended over additional years.
4. Check for Optional Products and Additional Charges
Review whether products such as extended warranties, protection plans or other optional services have been included in the financed amount.
Even where an optional product does not change the interest rate, financing its price can increase the amount borrowed and the total interest paid.
5. Check the Repayment Conditions
Understand whether you can make additional payments or repay the loan early, and whether any charges or conditions apply.
Do not assume all car loans have identical early repayment rules.
6. Make Sure the Vehicle Fits Your Budget
Calculate the total cost of owning the vehicle, not just the loan payment.
Allow room for insurance, registration, fuel, servicing, repairs and unexpected expenses.
A competitive rate is of limited benefit if the vehicle itself is too expensive for your circumstances.
What If Your Car Loan Rate Is Higher Than Expected?
A higher-than-expected offer does not necessarily mean every lender will provide the same rate.
Before accepting the loan, consider whether you can improve the overall financing arrangement.
- Review your credit reports: Check for inaccuracies or outdated information that may affect your credit profile.
- Reduce existing debt: Lower outstanding balances may improve affordability and, over time, your credit position.
- Increase your down payment: Borrowing less can reduce monthly payments and total interest costs.
- Consider a less expensive vehicle: A smaller loan may be more manageable even if the interest rate remains unchanged.
- Compare other lenders: Eligibility criteria and financing offers can differ.
- Consider delaying the purchase: If the total cost is too high, allowing time to improve your finances may be preferable to accepting an unaffordable loan.
Borrowers with previous credit difficulties can also explore our guide to bad credit car loans in Canada, which explains some of the additional considerations involved.
Can You Get a Better Car Loan Rate After You Have Already Signed?
Possibly. Some borrowers explore refinancing when their credit profile improves, market conditions change or another lender offers more suitable terms.
Refinancing involves replacing an existing loan with a new financing agreement.
However, a lower interest rate does not automatically mean refinancing will save money. You also need to consider any fees, repayment charges and changes to the remaining loan term.
For example, extending the loan may lower the monthly payment while increasing the total amount of interest you pay.
Compare the total remaining cost of your current loan with the total cost of the proposed replacement before making a decision.
Learn more in our guide to car loan refinancing in Canada.
Should You Get Car Loan Pre-Approval Before Shopping?
Car loan pre-approval or an initial financing assessment may help you understand your potential borrowing budget before choosing a vehicle.
However, the meaning of pre-approval varies between lenders and financing providers. An initial assessment is not necessarily a final commitment to lend.
Final approval and financing terms may depend on additional checks, the vehicle selected and the lender’s requirements.
Before applying, ask whether the process involves a hard credit enquiry and whether your information may be submitted to multiple financing providers.
Our guide to car loan pre-approval in Canada explains the process in more detail.
Frequently Asked Questions About Good Car Loan Rates in Canada
What is considered a good car loan rate in Canada in 2026?
A good car loan rate is one that is competitive for your credit profile, vehicle and repayment term. The Bank of Canada reported a 6.66% average for newly advanced and renewed auto loans at reporting chartered banks in July 2026, but this is a market benchmark rather than a guaranteed or universally suitable rate.
Is 5% a good car loan interest rate in Canada?
A 5% interest rate may be competitive relative to the July 2026 Bank of Canada bank-auto-lending benchmark, but whether it is a good offer depends on the vehicle, financing charges, repayment term and other available options. Compare the disclosed APR and total borrowing cost before deciding.
Is 7% a good car loan rate in Canada?
A 7% rate may be reasonable in some circumstances, but it is not automatically good for every borrower. Compare offers for the same vehicle, amount financed and repayment term, and consider the disclosed APR and total cost of borrowing.
Is 10% a high car loan interest rate in Canada?
A 10% rate is above the Bank of Canada’s July 2026 average for newly advanced and renewed auto loans at reporting chartered banks. However, that benchmark does not include every lender or borrower profile. Whether a 10% offer is competitive depends on your circumstances and the alternatives available.
What is a good car loan rate with excellent credit?
Borrowers with excellent credit may qualify for competitive financing offers, but there is no official Canadian APR guaranteed for an excellent credit score. Vehicle eligibility, income, debt obligations, loan term and lender policies can all influence the rate.
Are used car loan rates usually higher than new car loan rates?
Used car financing may carry higher rates, particularly where new vehicles qualify for manufacturer-supported promotions. However, the actual difference depends on the lender, vehicle age, condition and borrower profile.
Does a longer car loan mean a higher interest rate?
Not always. Lenders may price different terms differently, but a longer term does not automatically mean a higher APR. At the same loan amount and interest rate, however, extending the repayment period generally increases the total interest paid.
Can I negotiate a car loan interest rate in Canada?
You may be able to negotiate or obtain a more competitive offer by comparing lenders and dealership financing arrangements. The Financial Consumer Agency of Canada recommends shopping around and reviewing multiple financing options before signing.
Should I compare APR or monthly payments?
Compare both, along with the total amount financed, repayment term, financing charges and total cost of borrowing. A lower monthly payment may result from a longer loan rather than a better financing offer.
Can I get a lower car loan rate if my credit improves?
Improving your credit profile may help you qualify for more competitive financing in the future. If you already have a loan, refinancing may be an option, but approval is not guaranteed and any potential savings should be assessed after fees and changes to the repayment term.
Final Thoughts: Finding a Good Car Loan Rate in Canada
A good car loan rate is not defined by one percentage or credit-score threshold.
The Bank of Canada’s published lending statistics can help you understand the broader market, but your own financing offer needs to be assessed against your credit profile, the vehicle, the repayment term and the total borrowing cost.
Before signing, compare multiple offers where possible, understand all applicable charges and choose a repayment structure that leaves room for your other financial commitments.
Start by using our car loan calculator to estimate how different interest rates and terms could affect your payments.
If you would like to explore available vehicle financing options, you can apply online with ZoomCarLoans. Any available financing offers and approval depend on the lender’s eligibility and assessment criteria.


The ZoomCarLoans Editorial Team brings you practical advice on car financing, credit building, and vehicle buying in Canada. Our goal is to make car loans easier to understand — and easier to get approved for.