Car Loan After Consumer Proposal in Canada
March 06, 2026
Last updated: October 2026
Can you get a car loan after a consumer proposal in Canada? Yes, it may be possible to qualify for vehicle financing after completing a consumer proposal. Some lenders may also consider applications while a proposal is still active. Approval depends on the lender’s requirements, your credit history, income, existing financial obligations and ability to afford the vehicle.
A consumer proposal does not automatically prevent you from applying for a car loan, but it can limit your financing options and affect the interest rates offered.
This guide explains how car financing works during and after a consumer proposal, when to consider applying, what lenders assess, how credit-reporting timelines work and how to avoid taking on unaffordable debt.
What Is a Consumer Proposal in Canada?
A consumer proposal is a formal debt-resolution process under Canada’s Bankruptcy and Insolvency Act.
It is administered by a Licensed Insolvency Trustee (LIT), who helps develop an offer to eligible creditors to repay part of what you owe, extend the repayment period or both.
A consumer proposal cannot last longer than five years.
Unlike bankruptcy, a consumer proposal generally allows you to keep your assets, provided you continue meeting applicable obligations, including payments to secured creditors.
For example, if you already have a car loan secured against your vehicle, filing a consumer proposal does not normally eliminate that debt. You generally need to continue making the required payments to keep the car.
Official source: Office of the Superintendent of Bankruptcy Canada — Consumer Proposals.
Can You Get a Car Loan During a Consumer Proposal?
It may be possible to obtain car financing while your consumer proposal is active. However, not every lender accepts applicants with an ongoing proposal.
Some lenders may consider an application where the borrower has sufficient income, a manageable budget and a demonstrated ability to meet existing obligations.
Factors that may affect the decision include:
- Your employment and income stability.
- Your monthly consumer proposal payment.
- Your rent or mortgage and other living expenses.
- Your existing debts and financial commitments.
- Your payment history since filing the proposal.
- The vehicle’s purchase price, age and condition.
- The proposed down payment and repayment term.
Important: Being legally able to apply for financing does not mean approval is guaranteed or that taking on a new loan is advisable.
If your proposal is active, consider discussing the proposed car purchase with your Licensed Insolvency Trustee before committing to additional debt.
Can You Get a Car Loan After Completing a Consumer Proposal?
Yes. Completing a consumer proposal may improve your position when applying for new credit, particularly if your finances have stabilized and you have established a record of meeting your obligations.
However, completion does not automatically restore your credit score or guarantee access to standard car loan rates.
Lenders may still consider:
- Whether the proposal is shown as completed on your credit report.
- Your payment history before and after the proposal.
- Any outstanding debts or collections.
- Your current income and expenses.
- The amount you want to borrow.
- The lender’s own eligibility and affordability criteria.
Once you have fulfilled your proposal obligations, your Licensed Insolvency Trustee issues a certificate of full performance.
Keep this document. It can help you verify the completion of your proposal and address inaccurate information on your credit reports.
When Is the Best Time to Apply for a Car Loan?
There is no universal waiting period that guarantees approval or a better interest rate after a consumer proposal.
The most suitable time depends on your need for transportation, financial stability and the financing options available.
| Consumer Proposal Status | What to Consider |
|---|---|
| Recently filed | Your credit profile may have changed significantly. Financing options can be limited, and you should confirm that new payments will not interfere with proposal obligations. |
| Active and payments up to date | A consistent payment record may help demonstrate financial stability, but lenders can still decline applications or offer expensive financing. |
| Recently completed | You can provide proof of completion, although the proposal may remain on your credit report and influence lender decisions. |
| Completed and credit profile improving | Additional positive payment history and reduced debt may improve your options over time, depending on lender criteria. |
This table describes considerations at different stages. It does not represent approval probabilities, lender policies or guaranteed interest-rate improvements.
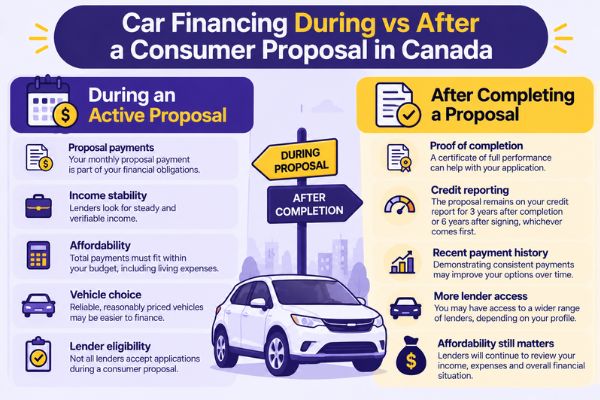
If you urgently need a reliable vehicle for work or family responsibilities, applying during a proposal may be worth exploring. If the purchase can wait, reducing debt and building savings first may provide more flexibility.
How Long Does a Consumer Proposal Stay on Your Credit Report?
Completing a consumer proposal does not mean it immediately disappears from your credit report.
According to the Financial Consumer Agency of Canada, Equifax and TransUnion generally remove consumer proposal information:
- Three years after you have paid off the debts included in the proposal, or
- Six years after you signed the proposal,
whichever occurs first.
For example, if you sign a consumer proposal in January 2024 and complete it in January 2026, the general three-year reporting period would point to January 2029. The six-year period from signing would end in January 2030, so January 2029 would generally be the earlier removal point.
That is an illustrative timeline, not a guarantee about the exact date an individual credit bureau will update a particular file.
Other negative information, such as missed payments or collection accounts, may have separate reporting periods.
Official source: Financial Consumer Agency of Canada — How Long Information Stays on Your Credit Report.
What Do Car Loan Lenders Look for After a Consumer Proposal?
1. Stable, Verifiable Income
Lenders generally want evidence that you have sufficient income to make the proposed car payments.
Depending on the lender, this may involve reviewing pay statements, employment details, bank statements or documentation of self-employment income.
2. Your Current Financial Commitments
During an active proposal, the required proposal payment forms part of your monthly financial obligations.
Lenders may also assess housing costs, other debt payments and living expenses when determining affordability.
3. Recent Payment History
A record of making required payments on time may help demonstrate financial stability.
However, paying your proposal consistently does not guarantee that a particular lender will approve you or offer a lower rate.
4. Vehicle Price and Eligibility
A reasonably priced vehicle may be easier to fit into your budget than an expensive model.
Lenders may also have restrictions relating to vehicle age, mileage, condition or purchase source.
5. Down Payment
A larger down payment reduces the amount financed and may improve affordability.
It may also reduce the lender’s exposure, although it does not guarantee approval or a particular interest rate.
What Interest Rate Can You Expect After a Consumer Proposal?
There is no official Canadian car loan interest-rate table based on whether a consumer proposal is active or completed.
Applicants with a recent proposal may face fewer financing options or higher borrowing costs than applicants with stronger credit histories.
However, the rate offered depends on the lender, the vehicle, your financial circumstances and the proposed loan terms.
Rather than relying on an advertised rate range, compare the actual offers available to you and pay attention to the annual percentage rate (APR) and total cost of borrowing.
How Interest Rates Affect the Cost of a Car Loan
Consider a $20,000 vehicle loan repaid over 60 months at different fixed annual interest rates.
| Annual Interest Rate | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|
| 7% | $396 | $3,761 |
| 10% | $425 | $5,496 |
| 15% | $476 | $8,548 |
| 20% | $530 | $11,793 |
Example assumptions: $20,000 financed over 60 months at a fixed annual interest rate, with monthly compounding and equal monthly payments. Figures are approximate and rounded. Taxes, fees, optional products and other charges are excluded. The rates are illustrative, not quoted rates for borrowers with consumer proposals.
At 7%, the estimated total interest is approximately $3,761. At 20%, it rises to approximately $11,793.
That is a difference of roughly $8,031 in interest on the same amount borrowed.
Use our car loan calculator to compare financing scenarios, or review our guide to car loan rates in Canada.
Can a Car Loan Help Rebuild Credit After a Consumer Proposal?
A car loan may contribute to rebuilding your credit history if the lender reports the account to Equifax or TransUnion and you consistently make payments on time. The effect on your credit score will depend on your overall credit profile and the scoring model used.
However, taking out a loan does not automatically improve your credit score.
Your score can be influenced by several factors, including:
- Whether payments are reported to Equifax or TransUnion.
- Whether you pay on time.
- Your existing credit history and outstanding obligations.
- New credit enquiries and accounts.
- The scoring model used.
Late or missed car loan payments can harm your credit profile and may put the vehicle at risk if you default.
Do not take out an expensive car loan solely to rebuild credit. The interest cost may outweigh any potential credit benefit.
If you need transportation, choose financing based on affordability first. Any credit improvement should be considered a possible secondary benefit.
Should You Get Car Loan Pre-Approval After a Consumer Proposal?
Pre-approval or an initial financing assessment may help you understand possible borrowing limits before choosing a vehicle.
However, the meaning of pre-approval varies between financing providers.
Some assessments are preliminary, and final approval may depend on further verification and the specific vehicle selected.
Before applying, ask whether:
- The lender considers applicants with active or completed consumer proposals.
- The assessment involves a hard credit enquiry.
- Your application may be shared with multiple lenders.
- The quoted rate is conditional.
- Additional documents will be required.
For more information, read our guide to car loan pre-approval in Canada.
Documents You May Need for a Car Loan After a Consumer Proposal
Document requirements vary by lender, but applicants may be asked to provide:
- Government-issued identification.
- Recent pay statements or other proof of income.
- Employment or self-employment details.
- Proof of address.
- Recent bank statements.
- Details of existing financial commitments.
- Consumer proposal documentation, if requested.
- A certificate of full performance if the proposal has been completed.
- Information about the vehicle being financed.
See our car loan documents checklist for additional guidance.
What Happens to an Existing Car Loan During a Consumer Proposal?
If you already have a financed vehicle when you file a consumer proposal, the car loan is generally treated differently from unsecured debts included in the proposal.
A vehicle loan secured against the car normally remains subject to the financing agreement.
This means you generally need to continue making the required payments if you want to keep the vehicle.
Filing a consumer proposal does not automatically prevent a secured lender from enforcing its rights if you default.
If you are struggling with your existing car payments, speak with your Licensed Insolvency Trustee and lender before making changes or stopping payments.
The Office of the Superintendent of Bankruptcy explains that the stay of proceedings generally does not prevent collection activity relating to secured debts such as car loans.
How to Improve Your Car Financing Options After a Consumer Proposal
Check Your Credit Reports
Review your Equifax and TransUnion reports for inaccurate balances, outdated information or errors relating to the proposal’s completion.
If you have completed your proposal, keep your certificate of full performance available when resolving reporting issues.
Build an Affordable Budget
Calculate how much you can comfortably spend on transportation after housing, food, utilities, debt obligations and other essential expenses.
Include vehicle insurance, fuel, maintenance, registration and unexpected repairs.
Save for a Down Payment
Saving toward a down payment can reduce the amount borrowed and the total interest cost.
However, avoid using all your emergency savings to make the purchase.
Choose a Sensibly Priced Vehicle
Focus on reliability, suitability and overall ownership costs rather than the maximum amount a lender might approve.
A less expensive vehicle can help keep payments manageable even if the interest rate offered is relatively high.
Compare Financing Offers
Where possible, compare the APR, amount financed, repayment term, fees and total cost of borrowing across different options.
Do not judge an offer by its monthly payment alone. A longer repayment term can reduce the payment while increasing the total interest paid.
Consider Waiting If Financing Is Too Expensive
If you do not urgently need a vehicle, allowing time to improve your credit profile, reduce debt and save a larger down payment may be preferable to accepting expensive financing.
Common Mistakes to Avoid When Financing a Car After a Consumer Proposal
- Assuming approval is guaranteed: An active or completed proposal does not guarantee access to financing.
- Accepting the first offer: Compare available options where possible.
- Focusing only on monthly payments: Review the full borrowing cost and repayment term.
- Borrowing more than necessary: A higher loan amount can increase interest costs and financial pressure.
- Ignoring proposal obligations: New car payments must not compromise your ability to meet existing commitments.
- Taking a loan solely to build credit: Expensive borrowing is not necessary for everyone rebuilding their credit.
- Assuming completion removes the proposal immediately: Credit-reporting timelines can continue after the proposal has been fulfilled.
Frequently Asked Questions About Car Loans After a Consumer Proposal in Canada
Can I get a car loan during a consumer proposal in Canada?
It may be possible. Some lenders consider applicants with active consumer proposals, but approval depends on income, affordability, credit history and lender requirements. Not every lender accepts these applications.
Can I get a car loan immediately after completing a consumer proposal?
You may apply after completing a consumer proposal, but approval is not guaranteed. Lenders may still consider the proposal’s presence on your credit report, your recent payment history and your financial circumstances.
How long should I wait to apply for a car loan after a consumer proposal?
There is no universal waiting period that guarantees approval. The best time depends on your financial stability, transportation needs and the financing options available. Waiting may help if it allows you to reduce debt, save a down payment or improve your credit profile.
Are car loan interest rates higher after a consumer proposal?
They may be. A recent consumer proposal can limit financing options or lead to higher borrowing costs, but there is no official Canadian interest-rate range assigned to proposal status. Rates depend on the lender and your overall application.
Do I need a down payment for a car loan after a consumer proposal?
Not every lender requires a down payment. However, contributing one can reduce the amount financed and may improve affordability. It does not guarantee approval or a lower interest rate.
How long does a consumer proposal stay on my credit report?
According to the Financial Consumer Agency of Canada, consumer proposal information is generally removed three years after the debts included in the proposal are paid off or six years after the proposal is signed, whichever comes first.
Can a car loan help rebuild my credit after a consumer proposal?
It may help if the lender reports payments to a credit bureau and you make payments on time. However, taking out a car loan does not guarantee a higher credit score, and missed payments can damage your credit profile.
Can I keep my existing car during a consumer proposal?
Generally, you may keep a financed vehicle if you continue meeting the obligations to the secured lender. A consumer proposal does not normally eliminate the debt secured against the car.
Does pre-approval guarantee a car loan after a consumer proposal?
No. Pre-approval may be conditional and does not guarantee final financing. The lender may still need to verify income, review your credit profile and assess the vehicle being financed.
Can I refinance a car loan after my consumer proposal is completed?
Refinancing may be possible if a lender approves a replacement loan. Compare the new APR, fees, repayment conditions and remaining term before proceeding. A lower rate does not necessarily mean lower total borrowing costs.
Final Thoughts: Getting a Car Loan After a Consumer Proposal
A consumer proposal does not automatically prevent you from obtaining vehicle financing in Canada.
Some lenders may consider applications during an active proposal, while others may require completion or additional evidence of financial stability.
The most important considerations are whether the financing is affordable, whether the vehicle meets your needs and whether the total borrowing cost is reasonable.
If your proposal is still active, consider speaking with your Licensed Insolvency Trustee before taking on a new financial obligation.
You can explore our car loan guides, estimate payments with the car loan calculator or learn about bad credit car financing in Canada.
If you would like to explore potential financing options, you can apply online with ZoomCarLoans. Approval, rates and available financing arrangements depend on the lender’s eligibility and assessment requirements.


The ZoomCarLoans Editorial Team brings you practical advice on car financing, credit building, and vehicle buying in Canada. Our goal is to make car loans easier to understand — and easier to get approved for.